Savings

Start Your Savings Journey with iQ

null

Deposit Accounts

Your savings account is your passport to iQ membership privileges. We offer a bunch of easy ways to save:
Features

  • Smartphone-Money

    Access your accounts anytime, anywhere, with our user-friendly online banking platform and mobile app. Manage your finances on-the-go with features like mobile check deposit, bill pay, and account alerts.

  • ATM-Withdrawl

    A nationwide network that gives you access to 30,000 ATMs with absolutely no fees.

  • Cash-To-Card

    Direct deposit

  • Bank

    17 branches in SW Washington and Portland Metro area and a network of 5,000 branches and 30,000 ATMs nationwide

  • High-Five

    Member-owned and operated so you experience the benefits

It pays to be an iQ member, especially if you take advantage of our iQ Member Perks.

Click here for full account disclosures.

Application

Ready to Get Started?

  • Apply Online
  • call_FILL0_wght400_GRAD0_opsz48
    Call Us
  • Bank
    Visit Us In-Branch

Current Rates

Deposit Products

Youth Accounts

Youth Accounts

Rates Effective as of 03/30/2022

Balance Dividend Rate Annual Percentage Yield*
$0+ Dividend Rate 0.050% Annual Percentage Yield* 0.05%
Youth Shares:* Fees could reduce earnings on this account. Rate may change at any time after account is open. Youth accounts are for individuals aged 0-17. Click here for full account disclosures.
Easy Saver

Easy Saver

Rates Effective as of 3/30/2022

Balance Dividend Rate Annual Percentage Yield*
$0+ Dividend Rate 0.050% Annual Percentage Yield* 0.05%

Easy Saver: *Fees could reduce earnings on this account. Rate may change at any time after account is open. Click here for full account disclosures. Click here for Terms and Conditions.

Intelligent Savings

Rates Effective as of November 1, 2025

Description Interest Rate Annual Percentage Yield (APY) Minimum Balance Minimum to Open
Intelligent Checking Qualifying
$0—$25,000
Interest Rate 4.889% Annual Percentage Yield (APY) 5.00% Minimum Balance $0.00 Minimum to Open $0.00
Intelligent Checking Qualifying
$25,000+
Interest Rate 0.250% Annual Percentage Yield (APY) 0.25% Minimum Balance $0.00 Minimum to Open $0.00
Intelligent Checking Non Qualifying Interest Rate 0.050% Annual Percentage Yield (APY) 0.05% Minimum Balance $0.00 Minimum to Open $0.00
Interest Checking Interest Rate 0.050% Annual Percentage Yield (APY) 0.05% Minimum Balance $0.00 Minimum to Open $0.00
Regular Shares (Savings) Interest Rate 0.050% Annual Percentage Yield (APY) 0.05% Minimum Balance $100.00 Minimum to Open $5.00
IRA Shares Interest Rate 0.300% Annual Percentage Yield (APY) 0.30% Minimum Balance $0.00 Minimum to Open $0.00
Roth IRA Shares Interest Rate 0.300% Annual Percentage Yield (APY) 0.30% Minimum Balance $0.00 Minimum to Open $0.00
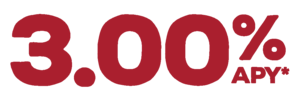
Intelligent Savings Qualifying Interest Rate 2.960% Annual Percentage Yield (APY) 3.00% Minimum Balance $0.00 Minimum to Open $0.00
Intelligent Savings Non Qualifying Interest Rate 0.050% Annual Percentage Yield (APY) 0.05% Minimum Balance $0.00 Minimum to Open $0.00

All Checking Accounts: *APY = annual percentage yield. Fees could reduce earnings on this account. Rate may change at any time after account is open. Click here for full account disclosures.


Truth-in-Savings Disclosure: Except as specifically described, the following disclosures apply to all accounts.

  • Rate Information. The Interest/Dividend Rate and Annual Percentage Yield (APY) on your accounts are set forth in the Personal Rate Schedule. The Annual Percentage Yield is a percentage rate that reflects the total amount of interest/dividends to be paid on an account based on the Interest/Dividend Rate and frequency of compounding for an annual period. The Interest/Dividend Rate may change monthly as determined by the Board of Directors. For all Money Market and IRA type share accounts, the rate may change weekly on Wednesdays as set by the Credit Union. If the Money Market balance drops below the Minimum Balance, then the interest rate will reflect the current share rate. Qualifying Intelligent Checking Accounts are tiered rate accounts. For these accounts, the interest rate applicable to a particular balance tier will apply only to the portion of the daily balance that is within the balance range for that tier. Terms and conditions to earn the Intelligent Checking rates apply, please see the Intelligent Checking Terms & Conditions for more information. Terms and conditions to earn the Intelligent Savings rate apply. Please see the Intelligent Savings Terms & Conditions for more information.
  • Nature of Dividends. Dividends are paid from current income and available earnings after required transfers to reserves at the end of the dividend period. The Dividend Rate and Annual Percentage Yield set forth in the Personal Rate Schedule are prospective rates that reflect the earnings the Credit Union anticipates paying for the Dividend Period.
  • Compounding and Crediting. For all accounts, interest/dividends will be compounded and credited monthly. The Dividend Period begins on the first calendar day of the month and ends on the last calendar day of the month.
  • Accrual of Interest/Dividends. Interest/dividends are calculated by the daily balance method, which applies a daily periodic rate to the principal in the account each day. Interest/dividends begin to accrue on cash and non-cash (e.g., checks) deposits on the business day you make the deposit to your account. For all accounts, except Money Market and IRA / SEP accounts, if you close your account before accrued interest/dividends are credited, accrued interest/dividends will not be paid. Fees could reduce the earnings on an account.
  • Balance Information. The minimum balance required to open each account is set forth in the Personal Rate Schedule. The minimum monthly balance required to avoid a service fee or obtain the stated Annual Percentage Yield is set forth in the Personal Rate Schedule. For Money Market accounts, there is a minimum balance required to avoid a service fee. For Primary Shares, Money Market, Secondary Shares (over 21) and IRA / SEP accounts, there is a minimum balance required to obtain the Annual Percentage Yield for the Dividend Period.
  • Account Limitations. For Non-Profit Organizations and Money Market accounts, transaction limitations may apply. We may limit to no more than six (6) preauthorized, automatic, overdraft, Online and Mobile Banking, telephonic or audio response transfers from those accounts to another account of yours or to a third party in any month. If you exceed these limitations, your accounts may be subject to a fee. Refer to the Membership & Account Agreement for additional information. Intelligent Checking accounts are limited to one per account. Intelligent Savings accounts are limited to one per account. Refer to the Personal Fee Schedule for current pricing. Refer to the Easy Saver Terms and Conditions for program details, including limitations on deposits and withdrawals.

All Savings Accounts: *APY = annual percentage yield. Fees could reduce earnings on this account. Rate may change at any time after account is open. Click here for full account disclosures. Truth-in-Savings Disclosure Except as specifically described, the following disclosures apply to all accounts

  1. Rate Information. The Interest/Dividend Rate and Annual Percentage Yield (APY) on your accounts are set forth in the Personal Rate Schedule. The Annual Percentage Yield is a percentage rate that reflects the total amount of interest/dividends to be paid on an account based on the Interest/Dividend Rate and frequency of compounding for an annual period. The Interest/Dividend Rate may change monthly as determined by the Board of Directors. For all Money Market and IRA type share accounts, the rate may change weekly on Wednesdays as set by the Credit Union. If the Money Market balance drops below the Minimum Balance, then the interest rate will reflect the current share rate. Qualifying Intelligent Checking Accounts are tiered rate accounts. For these accounts, the interest rate applicable to a particular balance tier will apply only to the portion of the daily balance that is within the balance range for that tier. Terms and conditions to earn the Intelligent Checking rates apply, please see the Intelligent Checking Terms & Conditions for more information. Terms and conditions to earn the Intelligent Savings rate apply. Please see the Intelligent Savings Terms & Conditions for more information.
  2. Nature of Dividends. Dividends are paid from current income and available earnings after required transfers to reserves at the end of the dividend period. The Dividend Rate and Annual Percentage Yield set forth in the Personal Rate Schedule are prospective rates that reflect the earnings the Credit Union anticipates paying for the Dividend Period.
  3. Compounding and Crediting. For all accounts, interest/dividends will be compounded and credited monthly. The Dividend Period begins on the first calendar day of the month and ends on the last calendar day of the month.
  4. Accrual of Interest/Dividends. Interest/dividends are calculated by the daily balance method, which applies a daily periodic rate to the principal in the account each day. Interest/dividends begin to accrue on cash and non-cash (e.g. checks) deposits on the business day you make the deposit to your account. For all accounts, except Money Market and IRA / SEP accounts, if you close your account before accrued interest/dividends are credited, accrued interest/dividends will not be paid. Fees could reduce the earnings on an account.
  5. Balance Information. The minimum balance required to open each account is set forth in the Personal Rate Schedule. The minimum monthly balance required to avoid a service fee or obtain the stated Annual Percentage Yield is set forth in the Personal Rate Schedule. For Money Market accounts, there is a minimum balance required to avoid a service fee. For Primary Shares, Money Market, Secondary Shares (over 21) and IRA / SEP accounts, there is a minimum balance required to obtain the Annual Percentage Yield for the Dividend Period.
  6. Account Limitations. For Non-Profit Organizations and Money Market accounts, transaction limitations may apply. We may limit to no more than six (6) preauthorized, automatic, overdraft, Online and Mobile Banking, telephonic or audio response transfers from those accounts to another account of yours or to a third party in any month. If you exceed these limitations, your accounts may be subject to a fee. Refer to the Membership & Account Agreement for additional information. Intelligent Checking accounts are limited to one per account. Intelligent Savings accounts are limited to one per account. Refer to the Personal Fee Schedule for current pricing. Refer to the Easy Saver Terms and Conditions for program details, including limitations on deposits and withdrawals.


* Fees could reduce earnings on these accounts. Rates may change at any time, including after account is opened.

*APY= Annual Percentage Yield.

Intelligent Savings: Qualifying 3.00% APY accurate as of November 1, 2025. To earn the qualified Intelligent Savings Rate, you must have an Intelligent Checking Account and meet all monthly qualifiers. If account requirements are not met, the non-qualifying rate will be 0.05% APY. Existing savings accounts cannot be converted to an Intelligent Savings—a new account must be opened.

Calculators & Tools

Use our helpful calculators to help guide your financial decisions

Save for a Rainy Day

Rainy Day Savings Summary
Planned Savings
$ 0.00
Savings Goal
$ 0.00
Saving for a Rainy Day
Comparison Details
Category Your Plan Your Goal

Life has a way of throwing surprises your way — a sudden medical bill, an unexpected car repair, or a gap between paychecks. Having money set aside for these moments can be the difference between a stressful setback and a manageable one. Start by estimating what you'd need: a buffer for unexpected costs plus enough to cover your essential monthly expenses for however long you'd want breathing room. Then map out how to get there using what you already have saved, what you can contribute each month, and the timeline that works for you. This calculator is for informational purposes only and is not intended as financial advice. Results are estimates based on the inputs you provide and assumptions about rates of return, which may vary. Please consult a qualified financial professional before making decisions about your savings strategy.

Disclosures

  • *APY = annual percentage yield

    All Certificates: *Fees could reduce earnings on these accounts. Rates may change at any time after account opening. A penalty may be imposed for early withdrawal. Eligible for Member Perks bump upon qualification and request at CD opening. In order to receive Member Perks, your iQ account must feature a savings and checking account with a debit card, as well as enrollment in eStatements and our Easy Saver program. New members must meet membership qualifications. Business certificates are not eligible for Member Perks bump. Click here for full account disclosures.

    1 7-month CD special: At maturity, promotional certificate will mature into a 6-month certificate, at then-current rate.

    2 19-month CD special: At maturity, promotional certificate will mature into a 12-month certificate, at then-current rate.

    Rates are accurate as of September 9, 2026. Offer is subject to change and may be discontinued at any time, but no earlier than September 9, 2026. No minimum deposit. New members must meet membership qualifications. For existing members to qualify for promotion, at least 50% of the funds used to open a new certificate must come from sources other than iQ Credit Union accounts. New memberships must be funded entirely from sources other than iQ Credit Union Accounts. 

    **Eligible for Member Perks bump upon qualification and request at CD opening. To receive Member Perks, your iQ account must feature a savings and checking account with an active debit card, as well as enrollment in eStatements and our Easy Saver program. Penalties may apply for early withdrawal. Fees could reduce earnings on these accounts. Federally insured by the NCUA.

    ** Business CDs do not qualify for the Member Perks .25% bump.

    Truth-in-Savings Disclosure: Except as specifically described, the following disclosures apply to all accounts.

    CERTIFICATE OF DEPOSIT(CD) ACCOUNTS

    1. Rate Information. The Interest Rate and Annual Percentage Yield (APY) on your Certificate accounts are set forth in the Personal Rate Schedule. For all Certificate accounts, the Interest Rate and Annual Percentage Yield are fixed and will be in effect for the term of the account. The Annual Percentage Yield is based on an assumption that interest will remain on deposit until maturity. A withdrawal of interest will reduce earnings.
    2. Compounding and Crediting. Interest will be compounded and credited quarterly for all certificate accounts. The interest period for all Certificate accounts begins on the first calendar day of the quarter and ends on the last calendar day of the quarter.
    3. Balance Information. The minimum balance required to open each account is set forth in the Personal Rate Schedule. The minimum monthly balance required to avoid a service fee or obtain the stated Annual Percentage Yield is set forth in the Personal Rate Schedule.
    4. Accrual of Interest. Interest begins to accrue on cash and non-cash (e.g. checks) deposits on the business day you make the deposit to your account. Interest is calculated by the daily balance method which applies a daily periodic rate to the principal in the account each day. For Regular Certificate accounts, you may elect at account opening to have accrued interest remain in the account and compound or transferred to another iQ account you own.
    5. Transaction Limitations and Fees. For both Regular and IRA Certificates, you may not make additional deposits after your account is opened. Earnings credited to this account may be withdrawn without penalty at any time during the term in which earned. No partial withdrawals of principal are allowed during the term of the account.
    6. Maturity. Your account will mature on the maturity date set forth on your Account Receipt or Maturity Notice.
    7. Early Withdrawal Penalty. We may impose a penalty if you withdraw any of the principal of your Certificate account before the maturity date.
      1. Amount of Penalty. The amount of the early withdrawal penalty is based on the following penalty schedule:
        1. For CDs with a maturity term of twelve (12) months or less, the penalty is 90 days’ interest regardless of when you redeem the account prior to maturity.
        2. For CDs with a maturity term greater than twelve (12) months up to 35 months, the penalty is 180 days’ interest regardless of when you redeem the account prior to maturity.
        3. For CDs with a maturity term greater than 35 months, the penalty is 270 days’ interest regardless of when you redeem the account prior to maturity.
        For all certificate accounts, there is a minimum penalty of 7 days’ interest for withdrawals made in the first 6 days.
      2. How the Penalty Works. The penalty is calculated as a forfeiture of part of the interest that has been or would be earned at the interest rate on the account. It applies whether or not the interest has been earned. In other words, if the account has not yet earned enough interest or if the interest has already been paid, the penalty will be deducted from the principal.
      3. Exceptions to Early Withdrawal Penalties. At our option, we may pay the account before maturity without imposing an early withdrawal penalty under the following circumstances:
        1. When an account owner dies or is determined legally incompetent by a court or other body of competent jurisdiction.
        2. When the account is an Individual Retirement Account (IRA) and any portion is paid within seven (7) days after establishment; or where the account is a Simplified Employee Pension Plan (SEP) provided that the depositor forfeits an amount at least equal to the simple interest earned in the amount withdrawn; or where the account is an IRA or SEP and the owner attains age 70 ½ or becomes disabled.
    8. Renewal Policy. Your Certificate accounts are automatically renewable accounts. You have a grace period of ten (10) calendar days after maturity in which to withdraw funds in the account without being charged an early withdrawal penalty. Unless the Credit Union has received different instructions from you, prior to the maturity of your account, your Certificate account will automatically renew for the same term at the rate in effect on the day of maturity.
    9. Promotional or Special Certificates. Promotional or Special Certificates may be offered from time to time. They will mature to the next shorter, regularly offered term and to the corresponding rate in effect on the day of maturity. They may require different terms and conditions as set forth on the Personal Rate Schedule. They may not be combined with any other offer. If the certificate has a “bump” feature, the bump is only available once during the original term of the certificate and only upon request. At the time the bump is requested, the rate of the existing certificate will be increased to the then-current rate of the non-promotional certificate currently offered with the next longer term.
    10. Nontransferable/Nonnegotiable. Your account is nontransferable and nonnegotiable. The funds in your account may not be pledged to secure any obligation of an owner, except obligations with the Credit Union.
  • Intelligent Checking®: Rates Effective as of November 1, 2025. All rates subject to change. No monthly fee. To earn the Intelligent Checking rate of 5.00% APY on balances up to and including $25,000, and 0.25% APY on balances over $25,000, you must meet the following monthly requirements: twelve (12) debit or credit card transactions; direct deposit of $100 or more per month, log in to online banking at least once per month; and receive e-Statements. If account requirements are not met, the non-qualifying rate will be 0.05% APY. New accounts will receive the qualifying dividend rate for the first statement cycle. Existing accounts converted to Intelligent Checking may qualify to receive the qualifying dividend rate beginning on the first day of the month following the month in which the account is converted. All requirements must be met with transactions posted and cleared by the close of business on the day before the last day of the month. ATM transactions do not count toward the 12 debit card transactions. Dividend paid on the last day of the month in which it is earned. Qualifiers must all be on the same account.

    **Only accounts that meet the Intelligent Checking criteria are eligible for the $25 ATM fee refund. Visit www.iQcu.com for details about how the ATM fee refund is calculated and other limitations. If your account has been open for at least thirty days and is in good standing, iQ Credit Union may, but is not obligated, to pay overdrafts on your account. An overdraft can occur when there are not sufficient funds in your account to pay an item presented against your account such as a check, electronic fund transfer or ACH, bill payment, or other debit on your account. A fee of up to $30 may be assessed for each overdraft. Overdrafts and subsequent fees are payable immediately; negative accounts must be brought positive within thirty days of the account going negative

  • *APY= Annual Percentage Yield.

    Intelligent Savings: Qualifying 3.00% APY accurate as of November 1, 2025. To earn the qualified Intelligent Savings Rate, you must have an Intelligent Checking Account and meet all monthly qualifiers. If account requirements are not met, the non-qualifying rate will be 0.05% APY. Existing savings accounts cannot be converted to an Intelligent Savings—a new account must be opened.

  • Money Market Accounts: * Fees could reduce earnings on these accounts. Rates may change at any time, including after account is opened. Click here for full account disclosures. Minimum balance of $1000 required to avoid monthly service fee.

  • All Savings Accounts: *APY = annual percentage yield. Fees could reduce earnings on this account. Rate may change at any time after account is open. Click here for full account disclosures. Truth-in-Savings Disclosure Except as specifically described, the following disclosures apply to all accounts

    1. Rate Information. The Interest/Dividend Rate and Annual Percentage Yield (APY) on your accounts are set forth in the Personal Rate Schedule. The Annual Percentage Yield is a percentage rate that reflects the total amount of interest/dividends to be paid on an account based on the Interest/Dividend Rate and frequency of compounding for an annual period. The Interest/Dividend Rate may change monthly as determined by the Board of Directors. For all Money Market and IRA type share accounts, the rate may change weekly on Wednesdays as set by the Credit Union. If the Money Market balance drops below the Minimum Balance, then the interest rate will reflect the current share rate. Qualifying Intelligent Checking Accounts are tiered rate accounts. For these accounts, the interest rate applicable to a particular balance tier will apply only to the portion of the daily balance that is within the balance range for that tier. Terms and conditions to earn the Intelligent Checking rates apply, please see the Intelligent Checking Terms & Conditions for more information. Terms and conditions to earn the Intelligent Savings rate apply. Please see the Intelligent Savings Terms & Conditions for more information.
    2. Nature of Dividends. Dividends are paid from current income and available earnings after required transfers to reserves at the end of the dividend period. The Dividend Rate and Annual Percentage Yield set forth in the Personal Rate Schedule are prospective rates that reflect the earnings the Credit Union anticipates paying for the Dividend Period.
    3. Compounding and Crediting. For all accounts, interest/dividends will be compounded and credited monthly. The Dividend Period begins on the first calendar day of the month and ends on the last calendar day of the month.
    4. Accrual of Interest/Dividends. Interest/dividends are calculated by the daily balance method, which applies a daily periodic rate to the principal in the account each day. Interest/dividends begin to accrue on cash and non-cash (e.g. checks) deposits on the business day you make the deposit to your account. For all accounts, except Money Market and IRA / SEP accounts, if you close your account before accrued interest/dividends are credited, accrued interest/dividends will not be paid. Fees could reduce the earnings on an account.
    5. Balance Information. The minimum balance required to open each account is set forth in the Personal Rate Schedule. The minimum monthly balance required to avoid a service fee or obtain the stated Annual Percentage Yield is set forth in the Personal Rate Schedule. For Money Market accounts, there is a minimum balance required to avoid a service fee. For Primary Shares, Money Market, Secondary Shares (over 21) and IRA / SEP accounts, there is a minimum balance required to obtain the Annual Percentage Yield for the Dividend Period.
    6. Account Limitations. For Non-Profit Organizations and Money Market accounts, transaction limitations may apply. We may limit to no more than six (6) preauthorized, automatic, overdraft, Online and Mobile Banking, telephonic or audio response transfers from those accounts to another account of yours or to a third party in any month. If you exceed these limitations, your accounts may be subject to a fee. Refer to the Membership & Account Agreement for additional information. Intelligent Checking accounts are limited to one per account. Intelligent Savings accounts are limited to one per account. Refer to the Personal Fee Schedule for current pricing. Refer to the Easy Saver Terms and Conditions for program details, including limitations on deposits and withdrawals.